

The Majors Have Run. The Juniors Haven’t.
Look past the current pullback, and the big picture is still clear: gold has made a powerful move, and gold and silver producers have followed. Yet many of the small companies at the bottom of the resource market have barely moved.
That gap may be the most important setup in the resource market today, and it’s why Palisades is positioned to benefit so significantly.
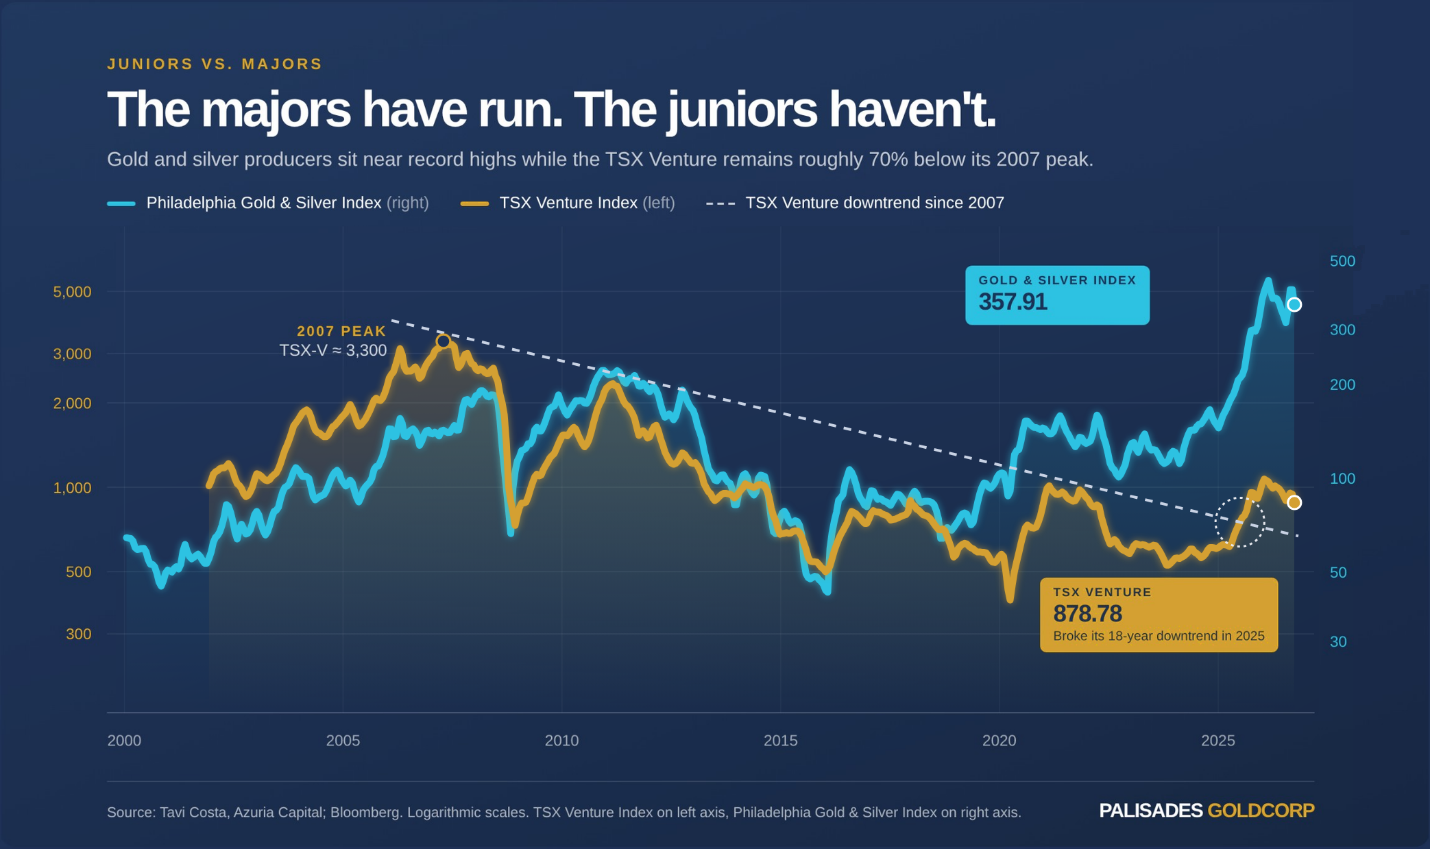
The chart above compares two indexes:
- The Philadelphia Gold & Silver Index (blue) tracks the major gold and silver producers. It has climbed from roughly 40 at its 2016 low to the mid-300s, breaking well above its 2011 peak and setting new records along the way.
- The TSX Venture Index (yellow) is home to Canada’s junior resource companies. It sits at about 879, still roughly 70% below its 2007 high.
The Venture Index isn’t a pure mining index, but it offers a useful window into the smaller end of the resource market. And what it shows is clear: so far, most of the gains in this bull market have gone to the larger, established names.
How Money Moves Through a Resource Bull Market
Resource bull markets tend to unfold in a predictable order:
- Investors buy the metal first.
- Once they’ve made money, they move into the plain-vanilla producers: large, liquid companies with real cash flow.
- Only after confidence is rebuilt do they look further down the market-cap ladder, into developers, explorers and juniors.
We are well into the second stage, with the majors re-rated, and the third stage may be starting: the Venture Index broke through its long-term downtrend line in 2025. But the juniors haven’t seen a real bull market yet.
If the third stage unfolds as it has in past cycles, money rotating from the majors into the juniors could move these much smaller stocks dramatically. A few hundred million dollars barely registers in a large producer. Spread across the Venture market, the same amount can send these stocks soaring.
Leverage on Leverage on Leverage
This is where Palisades comes in, because our exposure is built in layers.
Layer one: juniors are leveraged to the majors. When producers rise, juniors with deposits in the ground tend to rise further, because every move higher in metal prices makes their projects more economic.
Layer two: warrants are leveraged to the juniors. A warrant is the right, but not the obligation, to buy a share at a fixed price, so its value rises much faster than the stock itself. Take a warrant with a $0.40 exercise price on a stock trading at $0.50. It holds $0.10 of value. If the stock doubles to $1.00, the warrant is worth $0.60, six times its original value.
Layer three: Palisades holds those warrants by the billion. By participating in more than 450 private placements across over 330 companies, Palisades has built a portfolio of more than 1.7 billion warrants in junior gold, silver, copper, uranium and critical metals companies. Most investors can’t access these warrants, because getting them requires private placement allocations, capital and time.
The volume-weighted average expiry date on our warrants is November 13, 2028. With two years of runway, most of the portfolio has yet to be monetized. But where the setup has already played out, the results show what our model can deliver.
Ucore Rare Metals Inc. (TSX-V: UCU)
In June 2025, Palisades participated in Ucore’s financing for $3.6 million. We later sold the shares for $3.54 million, cutting our net cost to just $60,000, and held on to our warrants exercisable at $1.75. In Q4 2025, with the stock up roughly 9x from our entry, we exercised our warrants and sold the resulting shares for $10.2 million. The result is a net gain of $7.5 million, more than 100x our net cost.
Most of our warrants haven’t matured yet, but Ucore is not a one-off. Earlier this month, our Roxmore Resources (TSX: RM) warrants returned over 10x our net cost after SSR Mining agreed to acquire the company.
Copper Giant, Galway, and Silver Storm are just a few examples of meaningful warrant positions that Palisades has established and still holds.
The Next Move
In the next phase of this market, the ability to find the right small and mid-cap companies could become increasingly valuable. That has been Palisades’ work for years: reviewing deals, backing management teams early, and taking warrant positions before the broader market arrives.
The recent pullback adds to the opportunity. Juniors still need capital to advance their projects. For Palisades, that means adding positions at more attractive terms, leaving even more room for the portfolio to run when the market turns up.
If the money that has already flowed into gold and the majors makes its way down to the juniors, every layer of that leverage starts working at once. The juniors outperform the majors, our warrants outperform the juniors, and Palisades holds more than 1.7 billion of them.
The scale is what sets us apart. If our warrants averaged just $0.10 in-the-money, their intrinsic value would total $170 million.
The majors have had their run. The juniors are waiting their turn.
We will continue to keep you informed as developments unfold across our holdings.
Sincerely,
The Palisades Team
This material is for discussion purposes only. This is not an offer to buy or sell or subscribe or invest in securities. The information contained herein has been prepared for informational purposes using sources considered reliable and accurate, however, it is subject to change and we cannot guarantee the accurateness of the information. The material does not necessarily reflect the official policy or position of Palisades Goldcorp Ltd.